
Coastal Flood Insurance in 2026: What Homeowners Really Pay
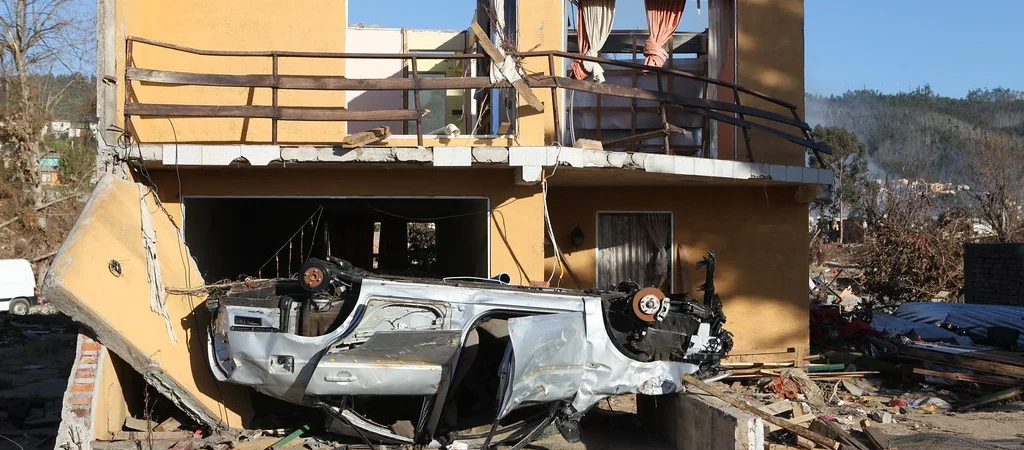
Most homeowners insurance does not cover flood damage. That single fact is why coastal flooding — from hurricanes, king tides, and heavy rain events — can deliver a financial blow measured in the tens of thousands of dollars to a home that no standard policy protects. In 2026, the National Flood Insurance Program (NFIP) is the main backstop for most homeowners, and coastal properties face the highest rates due to flood risk.
The headline numbers help set expectations. According to FEMA, about 37% of NFIP policies nationwide cost $1,000 or less per year, and roughly 32% cost between $1,000 and $2,000. But coastal and high-risk properties are a different story: typical new coastal policies can run $2,800 or more annually, with some outliers climbing well past that. If you live near the coast — or are shopping for a home there — flood insurance should be a line item in your real estate and budgeting math before you sign anything.
Why Your Homeowners Policy Won’t Cover Floods
Standard homeowners, condo, and renters insurance policies explicitly exclude flooding. Flood is defined broadly — water that came from outside your home, including storm surge, rising rivers, heavy rain, and surging coastal tides. Because this is the single most common natural disaster in the U.S., the exclusion is baked into standard policies, and the coverage is sold separately, almost always through the NFIP (with a growing private market in some states).
How NFIP Pricing Works Under Risk Rating 2.0
In 2021 FEMA rolled out Risk Rating 2.0, a new pricing model that replaced the old flood-zone-based pricing with a property-specific risk assessment. Instead of just being placed in a flood zone map, your premium now reflects the actual flood risk of your property: elevation, distance to water, building characteristics, replacement cost, and the specific flood history of the area. This means two homes in the same neighborhood can pay very different premiums, and coastal properties with high exposure typically see the biggest increases.
What this means for buyers:
- Coastal premiums rose faster than inland ones as the new model priced in storm surge and coastal flooding risk.
- Higher-risk homes now carry rates that reflect their true exposure, reducing the subsidy low-risk coastal homes once enjoyed.
- Your specific property’s elevation matters more than its flood zone letter under the new model.
Average Costs by Risk Profile in 2026
- Low to moderate risk (inland, lower elevation risk): often $400–$1,000 per year.
- Standard NFIP policy: national average around $700–$976 per year, or roughly $50–$81 per month, per recent analyses of 2026 rates.
- Coastal and high-risk properties: typically $2,000–$3,000+ per year, with outliers well above that depending on elevation and exposure.
Rates are quoted per policy, and you can price yours with the NFIP’s online quote tool (floodsmart.gov) before you commit to a home.
Mandatory Purchase Requirements and Lender Rules
If your home is in a high-risk flood zone (Special Flood Hazard Area, or SFHA) and you have a federally regulated mortgage, flood insurance is required. Lenders are required by law to verify coverage and can force-place a policy — often at a higher cost to you — if you let coverage lapse. If you own your home free and clear in a high-risk zone, coverage is not legally required, but the financial risk of skipping it is severe.
Private Flood Insurance vs. NFIP in Coastal Areas
A growing private flood insurance market in coastal states offers alternatives to the NFIP. Private policies can sometimes beat NFIP pricing for lower-risk homes, and they can offer higher coverage limits and broader terms. However, private pricing can be volatile after a big storm, and availability varies by state. In coastal areas where NFIP rates have jumped, it is worth getting quotes from both an NFIP-approved agent and one or two private markets before deciding.
How to Lower Your Coastal Flood Premium
- Get an elevation certificate. Showing your home sits above base flood elevation can cut your rate significantly under Risk Rating 2.0.
- Choose a deductible you can afford. Higher flood deductibles lower the premium but raise out-of-pocket risk.
- Mitigate flood risk: some communities offer discounts, and raising utilities or adding flood vents can help on newer structures.
- Bundle and shop. Some insurers and the NFIP offer discounts for bundling or for properties in CRS-participating communities (Community Rating System).
- Confirm the replacement cost basis matches your home — over-insuring raises your premium for no benefit.
Frequently Asked Questions
Is flood insurance mandatory for every coastal home?
Only if your home is in a high-risk flood zone and you have a federally regulated mortgage. But even so-called low-risk coastal areas can flood, so voluntary coverage is often worth it.
Does the NFIP cover personal belongings?
Yes, up to the policy’s personal property limit, but contents coverage is separate from building coverage and must be elected.
Is private flood insurance cheaper than the NFIP?
Sometimes, depending on your property. Get quotes from both, since private carriers can beat NFIP rates for lower-risk coastal homes.
What does flood insurance not cover?
Most flood policies exclude mold, moisture damage, and damage to items in basements. Read the exclusions carefully for coastal homes with basements.
Bottom Line
Coastal flood insurance is an unavoidable — and increasingly costly — reality for many homeowners in 2026. Budget $2,000–$3,000+ per year for coastal property, understand that Risk Rating 2.0 prices your actual risk rather than your zone, and get an elevation certificate to fight back against the highest rates. For buyers, build flood insurance into your total monthly cost before you fall in love with a home near the water. For more on financing and protecting property, browse our real estate guides.



